
Texas Tree Service Insurance
The Allen Thomas Group is an independent, family-owned insurance agency, licensed since 2003, that builds tree service insurance programs for Texas arborists and tree care contractors around a fact many out-of-state crews never expect: Texas is the only state where workers compensation is genuinely optional for most private employers. We shop your coverage, general liability, workers compensation, inland marine equipment coverage, commercial auto, and professional liability, across 15+ A-rated carriers, licensed in 28 states.
Carriers We Work With
Last Updated: September 29, 2026
What Is Tree Service Insurance in Texas?
Texas tree service insurance is the same core package described on our national tree service insurance page, general liability, workers compensation, commercial auto, inland marine equipment coverage, and professional liability, applied to a state with a genuinely unique workers compensation structure: Texas is the only state where coverage is optional for most private employers, and opting out carries real legal consequences worth understanding before making that call.
The biggest state-specific difference is that Texas puts a real decision in every employer's hands that most states never present at all. Choosing subscriber versus non-subscriber status isn't just a paperwork choice, it changes the legal defenses available if an employee is ever injured, which means the decision deserves a real conversation with an agent rather than a default assumption either way.
Why Texas Tree Care Companies Face a Different Risk Picture
Texas's defining fact for this trade is legal and structural, not weather-driven, and it is unique among all 28 states in this build.
Texas Is the Only State Where Workers Comp Is Optional
The Texas Department of Insurance's Division of Workers' Compensation confirms private employers can choose not to carry workers compensation coverage in most cases. Employers who opt out, called non-subscribers, must report their non-coverage status and any lost-time injuries or deaths to the state.
Opting Out Means Losing Key Legal Defenses
Texas Labor Code Section 406.033 strips non-subscriber employers of three common-law defenses in an employee injury lawsuit, contributory negligence, assumption of the risk, and the fellow-servant rule, shifting the burden of proof onto the employer instead of the employee. This is a serious consideration for a trade with real fall and equipment-related injury risk.
Austin's Heritage Tree Ordinance Adds a City-Level Permit Layer
Austin's Tree Ordinance, administered by the City Arborist Program, requires a permit to remove or impact a regulated tree, and heritage trees of 19 inches or more in diameter at breast height require both a permit and an approved variance before removal, a real regulatory layer for crews working in the Austin market.
Core Insurance Coverages for Texas Arborists
The coverage types match the national tree service program: general liability, workers compensation (or a deliberate non-subscriber strategy), commercial auto, inland marine, and professional liability, all shopped across our full carrier panel.
General Liability Insurance
General liability covers the property-damage exposure of tree removal work, and becomes even more important as a liability backstop for a company that chooses non-subscriber status on the workers comp side.
Workers Compensation Insurance
Optional for most Texas employers, filed under classification 0106 for subscribers, but choosing not to subscribe carries real legal consequences under Texas Labor Code Section 406.033 that deserve a careful conversation with your agent before deciding.
Commercial Auto Insurance
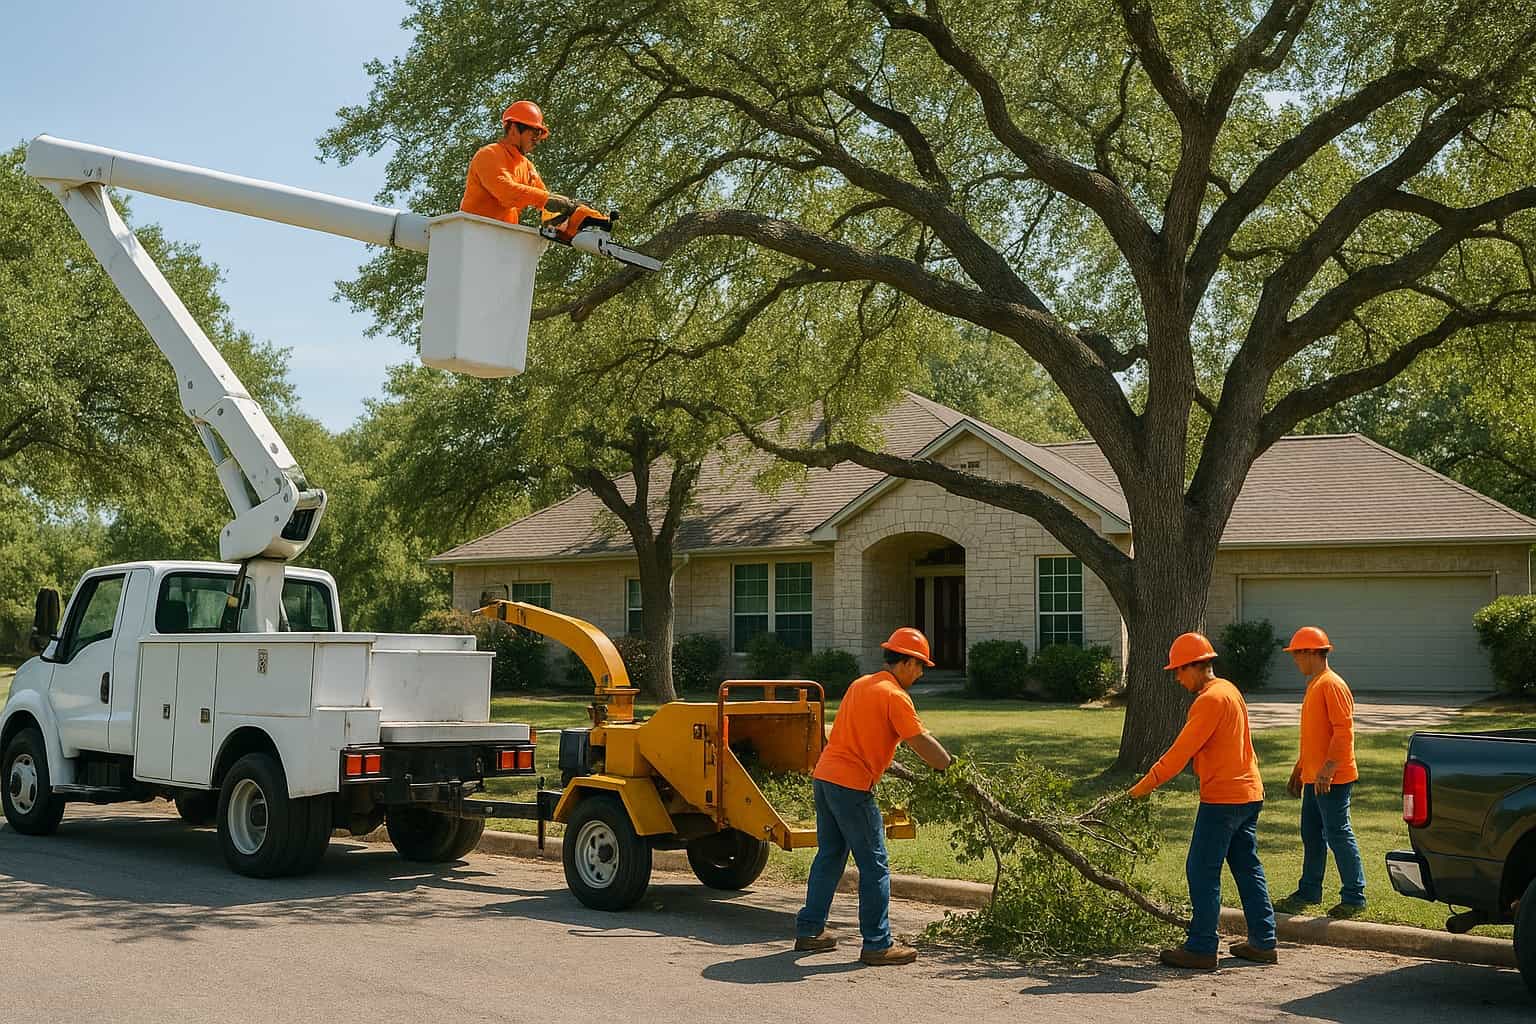
Commercial auto covers the trucks and chipper trailers your crews rely on to move between job sites across a state as large as Texas.
Inland Marine (Tools and Equipment)
Chainsaws, stump grinders, and crane attachments are covered wherever they travel across the state, whether stolen from a truck overnight or damaged on a job site.
Professional Liability (E&O)
Texas arborists who perform paid tree health assessments or heritage-tree variance consulting should carry professional liability alongside general liability.
How Much Does Tree Service Insurance Cost in Texas?
General liability pricing in Texas falls in the same national range described on our tree service insurance page, roughly $750 to $2,300 per year for a small operation, driven by crew size, equipment, and whether crane-assisted removals or severe-weather cleanup are part of the regular work. Because Texas allows non-subscriber status, a company's overall insurance cost picture depends heavily on that decision: a non-subscriber typically carries higher general liability and umbrella limits to offset the lost common-law defenses, while a subscriber's workers comp premium is rated normally under classification 0106.
Key factors that drive Texas tree service premiums:
- Whether the business subscribes to workers compensation or opts out
- Payroll and crew size
- Prior claims history
- Volume of hail, ice-storm, or hurricane cleanup work
- Municipal or utility contract requirements for higher limits
How The Allen Thomas Group Can Help You
We shop your general liability, workers compensation, commercial auto, inland marine, and professional liability across 15+ A-rated carriers, and we walk Texas tree service owners through the subscriber-versus-non-subscriber decision so the rest of their program is built to match.
Licensing and Regulatory Notes for Texas Tree Care Businesses
The Texas Department of Insurance confirms workers compensation coverage is optional for most private employers, with non-subscribers losing key common-law defenses under Texas Labor Code Section 406.033. No state-level license exists for tree service or arborist work; the Texas Department of Licensing and Regulation's list of regulated trades does not include this category, so permitting is handled at the city level, with Austin's heritage-tree ordinance as one real, verified example.
Companies weighing non-subscriber status should have a real conversation with their agent about umbrella and general liability limits before deciding, since those coverages become the primary financial backstop once the common-law defenses in Texas Labor Code Section 406.033 are no longer available. Companies working in Austin or other cities with their own heritage-tree ordinances should confirm local permit rules before quoting a removal.
Common Texas Tree Service Claims and How Coverage Responds
Scenario 1: A Roof Is Damaged During a Dallas Removal
A crew removing a large tree in Dallas misjudges the drop zone and damages a homeowner's roof. This falls under the general liability policy's property damage coverage.
Scenario 2: A Non-Subscriber's Employee Is Injured
An employee of a non-subscribing tree service is injured on a job and sues; because the employer opted out of workers comp, it faces the suit without the common-law defenses subscribers retain. A properly structured liability program is essential in this scenario.
Scenario 3: Equipment Is Stolen from a Job Site
A stump grinder is stolen overnight from a job site trailer in Houston. This falls under inland marine (tools and equipment) coverage.
Scenario 4: An Unpermitted Heritage Tree Removal Is Cited
A crew removes an Austin heritage tree without the required permit and variance, and the city cites the contractor. This kind of regulatory-compliance dispute is the type of exposure professional liability is designed to help address.
Frequently Asked Questions
Is workers compensation mandatory in Texas?
No, not for most private employers. Texas is the only state where workers' compensation coverage is genuinely optional for most private employers, confirmed by the Texas Department of Insurance's Division of Workers' Compensation. Employers who opt out are called non-subscribers and must report their non-coverage status, plus any lost-time injuries or deaths, to the state.
What happens if a Texas tree service company chooses not to carry workers compensation?
Under Texas Labor Code Section 406.033, a non-subscribing employer loses three key common-law defenses in an employee injury lawsuit: contributory negligence, assumption of the risk, and the fellow-servant rule. This shifts the burden of proof onto the employer and can significantly increase the company's liability exposure in a workplace injury claim, which is especially relevant in a trade with real fall and equipment-related injury risk.
Does Texas require a state license for tree service companies?
No. The Texas Department of Licensing and Regulation does not list a tree service or arborist category among its regulated trades. Tree removal work in Texas is generally unlicensed at the state level, with permitting handled at the city level instead.
Does Austin require a permit to remove a tree?
Yes, for regulated and heritage trees. Austin's Tree Ordinance, administered by the City Arborist Program, requires a permit to remove or impact a regulated tree, and heritage trees of 19 inches or more in diameter at breast height require both a permit and an approved variance before removal.
What insurance does a tree service business need in Texas?
Most Texas tree service businesses need general liability as the foundation, workers compensation (or a clear-eyed non-subscriber liability strategy if opting out), inland marine for chainsaws and stump grinders, commercial auto for trucks and chipper trailers, and professional liability if they perform paid tree health assessments or consulting work.
How much does tree service insurance cost in Texas?
General liability for a small Texas tree service operation typically falls in the same $750 to $2,300 per year range seen nationally, driven by crew size, equipment, and whether crane-assisted removals or hail/ice-storm cleanup are part of the regular work.
Does ATG write tree service insurance throughout Texas?
Yes. The Allen Thomas Group writes tree service insurance programs for companies across Texas, including Austin, Dallas, and Houston. Call or request a quote to get started.
Get Your Texas Tree Service Insurance Program
The Allen Thomas Group is an independent, family-owned agency with access to 15+ A-rated carriers. One call gets you competitive rates from across the market, not a single carrier's take-it-or-leave-it quote. Certificates of insurance issued same day for active policies.