
Commercial Cleaning and Janitorial Business Insurance
The Allen Thomas Group is an independent, family-owned insurance agency that shops 15+ A-rated carriers to build coverage for commercial cleaning and janitorial companies, not a single-carrier captive agent locked into one company’s rates and terms. We work with cleaning businesses of every size, from a single owner-operator servicing a few offices to established janitorial companies running multiple crews and vehicles across commercial properties. Most quotes are ready within 1-3 business days. Click the button below to start your free quote, or call (440) 826-3676 to speak with a licensed agent directly.
Carriers We Represent


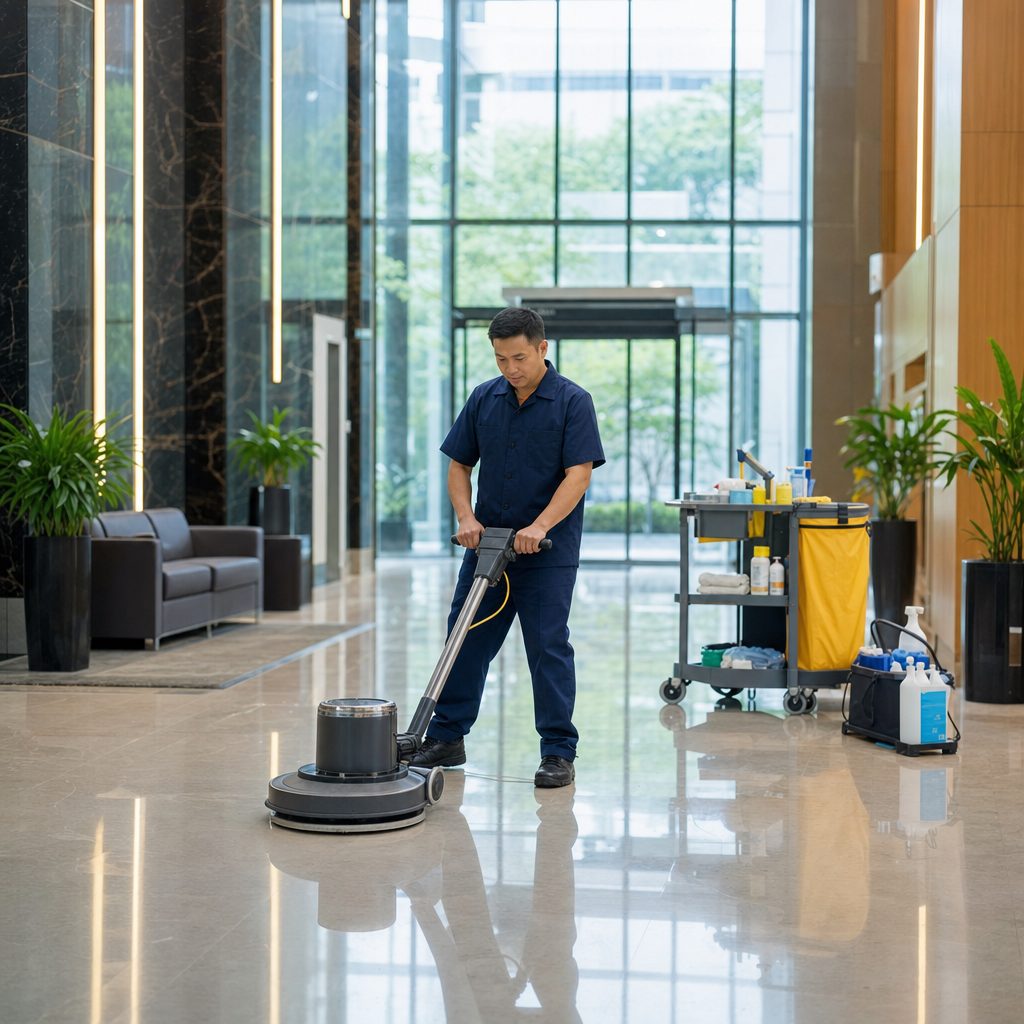
Commercial cleaning insurance is a specialized bundle of coverage, typically general liability, a janitorial bond, and workers’ compensation, built around the specific risk of sending employees into other people’s homes and businesses to clean them. Carrying it is often the deciding factor in winning a commercial contract, since most corporate clients require proof of coverage before letting a cleaning crew on site.
How Much Does Commercial Janitorial Insurance Cost?
Pricing depends heavily on which policies you carry together, your payroll and employee count, and the type of cleaning work you do. Here’s what the four core policies cost on their own:
| Policy | What It Covers | Average Cost |
|---|---|---|
| General Liability | Third-party bodily injury (a client slips on a wet floor) and accidental property damage (breaking an expensive office appliance) | $48 – $63/mo ($575 – $750/yr) |
| Workers’ Compensation | Medical expenses and lost wages if an employee is hurt on the job. Required by law in nearly every state once you hire your first employee | $130 – $208/mo ($1,560 – $2,500/yr) |
| Commercial Auto | Company vehicles used to transport equipment, cleaning chemicals, or crews between job sites | $165 – $173/mo ($1,979 – $2,076/yr) |
| Janitorial Bond | Reimburses a client if an employee steals money, equipment, or property while cleaning their facility | ~$11/mo |
Cost figures reflect national commercial cleaning industry insurance benchmarks, 2026.
Coverage Types for Commercial Cleaning & Janitorial Companies
Here’s what each policy actually covers, in plain terms, along with a link to the full coverage page where one exists:
General Liability Insurance
Covers third-party bodily injury and property damage your business causes while on a client’s premises.
Such as a client slipping on a wet floor after mopping, or a spilled chemical that damages a carpet. This is the coverage most commercial clients require before signing a cleaning contract, and it’s usually the first policy a new cleaning business buys.
Janitorial Bond
A surety bond, not insurance, that reimburses a client if an employee steals money or property while cleaning their home or business.
It covers theft specifically, not accidental damage, and helps establish trust with clients who won’t hire an unbonded cleaning company.
Workers’ Compensation Insurance
Required in nearly every state once a cleaning company has any employees, part-time or full-time.
Texas and South Dakota are the only exceptions, though it’s still recommended there. Covers medical expenses and partial lost wages if an employee is injured on the job, such as a fall from a ladder while cleaning high windows or light fixtures.
Commercial Auto Insurance
Required in nearly every state for vehicles owned by the business, covering property damage and medical bills from an accident.
Used to transport crews, equipment, or industrial chemicals between job sites.
Inland Marine (Tools & Equipment) Insurance
Covers cleaning equipment, such as floor buffers, carpet extraction machines, and ladders, while it’s in transit or on-site.
Commercial auto insurance covers the vehicle itself, not the equipment riding inside it, which is exactly the gap this coverage closes.
Business Owner’s Policy (BOP)
Bundles general liability with commercial property insurance into a single, typically lower-cost policy.
If you lease or own an office or storage space for your supplies, small, low-risk cleaning businesses are usually eligible, and inland marine coverage for equipment can often be added on top.
Commercial Umbrella Insurance
Adds additional liability limits on top of general liability, commercial auto, and employer’s liability coverage.
Cleaning companies bidding on larger commercial contracts often need this to meet a client’s required liability limit, sometimes as high as $2 million or $5 million.
Lost Key Coverage
Reimburses a commercial property for the cost of rekeying locks and reissuing keycard systems if your employee loses master keys.
This is a real, common gap in a standard cleaning-business policy. Larger commercial and multi-tenant properties increasingly ask about it specifically before signing a contract, usually added as an endorsement rather than a standalone policy.
What Influences Your Total Premium?
Your final price depends on a handful of specific risk factors, not just a flat industry rate:
- Scope of operations. Specializing in high-hazard cleaning, such as exterior high-rise window washing or biohazard and disaster cleanup, triggers significantly higher premiums than general office cleaning.
- Payroll and staff size. Workers’ compensation is calculated directly from your total payroll and employee count, so it’s the policy most affected by how many people you employ.
- Contract requirements. Some large commercial properties require $2 million or $5 million umbrella liability limits before they’ll let you sign a service agreement, which changes what coverage you actually need to bid on the work.
Why Bonding and Insurance Matter for Cleaning Companies
Commercial cleaning crews are given access to offices, retail spaces, and sometimes homes, often unsupervised and after hours. Property managers, business owners, and hosts of short-term rentals routinely require proof of both insurance and bonding before signing a contract or handing over keys and access codes. Being able to produce a certificate of insurance (a document verifying your active coverage and limits) and proof of a janitorial bond on request is now a standard part of winning and keeping commercial cleaning contracts, not an optional extra.
Commercial Cleaning and Janitorial Business Insurance FAQs
What insurance does a commercial janitorial or cleaning company actually need?
Most commercial cleaning companies need four core policies: general liability insurance, workers’ compensation if you have employees, commercial auto insurance if crews drive between job sites, and a janitorial bond to reimburse clients for employee theft. Companies that lease office or storage space, carry expensive equipment, or bid on larger commercial contracts often add a business owner’s policy, inland marine coverage, and commercial umbrella insurance on top of those four.
What is a janitorial bond, and is it the same thing as insurance?
A janitorial bond, also called a fidelity bond or business service bond, is a type of surety bond, not insurance. It reimburses a client if one of your employees steals money or property while cleaning their home or business. Unlike an insurance claim, a surety company that pays out on a bond claim expects your business to reimburse it afterward, so it protects your client’s trust in you more than it protects your own bottom line.
How much does commercial cleaning business insurance cost?
A standalone general liability policy averages $48 to $63 a month. Workers’ compensation typically runs $130 to $208 a month depending on payroll and employee count, and commercial auto insurance averages $165 to $173 a month per vehicle. A janitorial bond is much less, averaging around $11 a month. A cleaning company carrying all four policies together typically pays somewhere between $300 and $600 a month total.
Do I need workers’ compensation if I only have a few part-time cleaners?
In most states, workers’ compensation is required by law as soon as you have any employees, part-time or full-time, not just once you reach a certain headcount. Only Texas and South Dakota don’t legally require it, though it’s still recommended there. It covers medical bills and partial lost wages if an employee is injured on the job, such as a fall from a ladder while cleaning high surfaces.
Does my cleaning company’s insurance cover damage to a client’s property, or only theft?
General liability insurance covers accidental property damage, like a spilled cleaning chemical that ruins a client’s carpet. A janitorial bond covers something different: theft or dishonest acts by an employee. Most commercial cleaning companies need both, since they protect against two different kinds of loss.
Will my commercial auto insurance cover cleaning equipment I carry between job sites?
Not automatically. A standard commercial auto policy covers the vehicle itself and injuries or damage from an accident, not the buffers, vacuums, or extraction machines you’re transporting. Inland marine insurance is the coverage built specifically to protect cleaning equipment while it’s in transit or on a job site away from your main location.
What happens if my employee loses a client’s master keys or keycards?
This is a real, common gap in standard cleaning-business policies. Lost key coverage, usually added as an endorsement rather than a separate policy, reimburses a commercial property for the cost of rekeying locks and reissuing keycard systems if your employee loses master keys while on a job. Larger commercial and multi-tenant properties increasingly ask about this coverage specifically before signing a contract.
How do I get in touch with a licensed agent about coverage for my cleaning company?
Call (440) 826-3676 to speak directly with a licensed agent, or request a free quote online and a licensed agent will follow up to go over the specific coverage your cleaning business needs.
Get Coverage Built for Your Cleaning Business
Talk to a licensed agent who will shop 15+ A-rated carriers to find coverage that actually fits your crews, equipment, and contracts.