
Utah Tree Service Insurance
The Allen Thomas Group is an independent, family-owned insurance agency, licensed since 2003, that builds tree service insurance programs for Utah arborists and tree care contractors around a genuine legal carve-out: Utah runs one of the country's most comprehensive contractor licensing systems, yet specifically exempts tree removal from it by name. We shop your coverage, general liability, workers compensation, inland marine equipment coverage, commercial auto, and professional liability, across 15+ A-rated carriers, licensed in 28 states.
Carriers We Work With
Last Updated: September 30, 2026
What Is Tree Service Insurance in Utah?
Utah tree service insurance is the same core package described on our national tree service insurance page, general liability, workers compensation, commercial auto, inland marine equipment coverage, and professional liability, applied to a state with a genuinely deliberate regulatory carve-out for this exact trade.
The biggest state-specific difference is that Utah's contractor licensing law is otherwise broad and mandatory, which makes the tree-work exemption a real, specific legislative choice rather than a simple gap or oversight, a distinction worth understanding when talking to customers who assume all trades in Utah are licensed.
Why Utah Tree Care Companies Face a Different Risk Picture
Utah's defining fact for this trade is a specific, named exemption inside an otherwise comprehensive licensing law, verified directly against Utah's own administrative code.
Utah's Own Licensing Law Specifically Exempts Tree Removal
Utah Administrative Code R156-55a-301(4)(c), enforced by the Division of Professional Licensing, lists tree stump and tree removal among the specific activities exempt from Utah's contractor licensing law, even though Utah otherwise runs a broad, mandatory licensing regime with defined trade classifications. This is a deliberate legislative carve-out, not an oversight, and it means a Utah tree company operates in a genuinely unlicensed pocket inside a heavily regulated state.
Utah's Workers Comp Fund Went Fully Private
Utah's Workers Compensation Fund began in 1917 when the state legislature passed an act mandating coverage and created the State Insurance Fund, later renamed the Workers Compensation Fund. Unlike Montana's or Colorado's funds, which remain state-affiliated quasi-public carriers, Utah's fund has since converted into fully private stock insurance companies, domiciled in Utah and A-rated by AM Best, a genuinely different endpoint for the same kind of historical state fund.
Standard Private-Carrier Workers Compensation
Utah is a standard private-carrier state, not one of the four monopolistic-fund states, with tree pruning and removal typically filed under NCCI classification 0106.
Core Insurance Coverages for Utah Arborists
The coverage types match the national tree service program: general liability, workers compensation, commercial auto, inland marine, and professional liability, all shopped across our full carrier panel.
General Liability Insurance
General liability covers the property-damage exposure of removal work, and matters even more given Utah's licensing exemption, since a documented insurance program is one of the clearest ways a Utah tree company can demonstrate professionalism to a customer.
Workers Compensation Insurance
Required for Utah tree service crews under classification 0106, shopped across our full carrier panel.
Commercial Auto Insurance
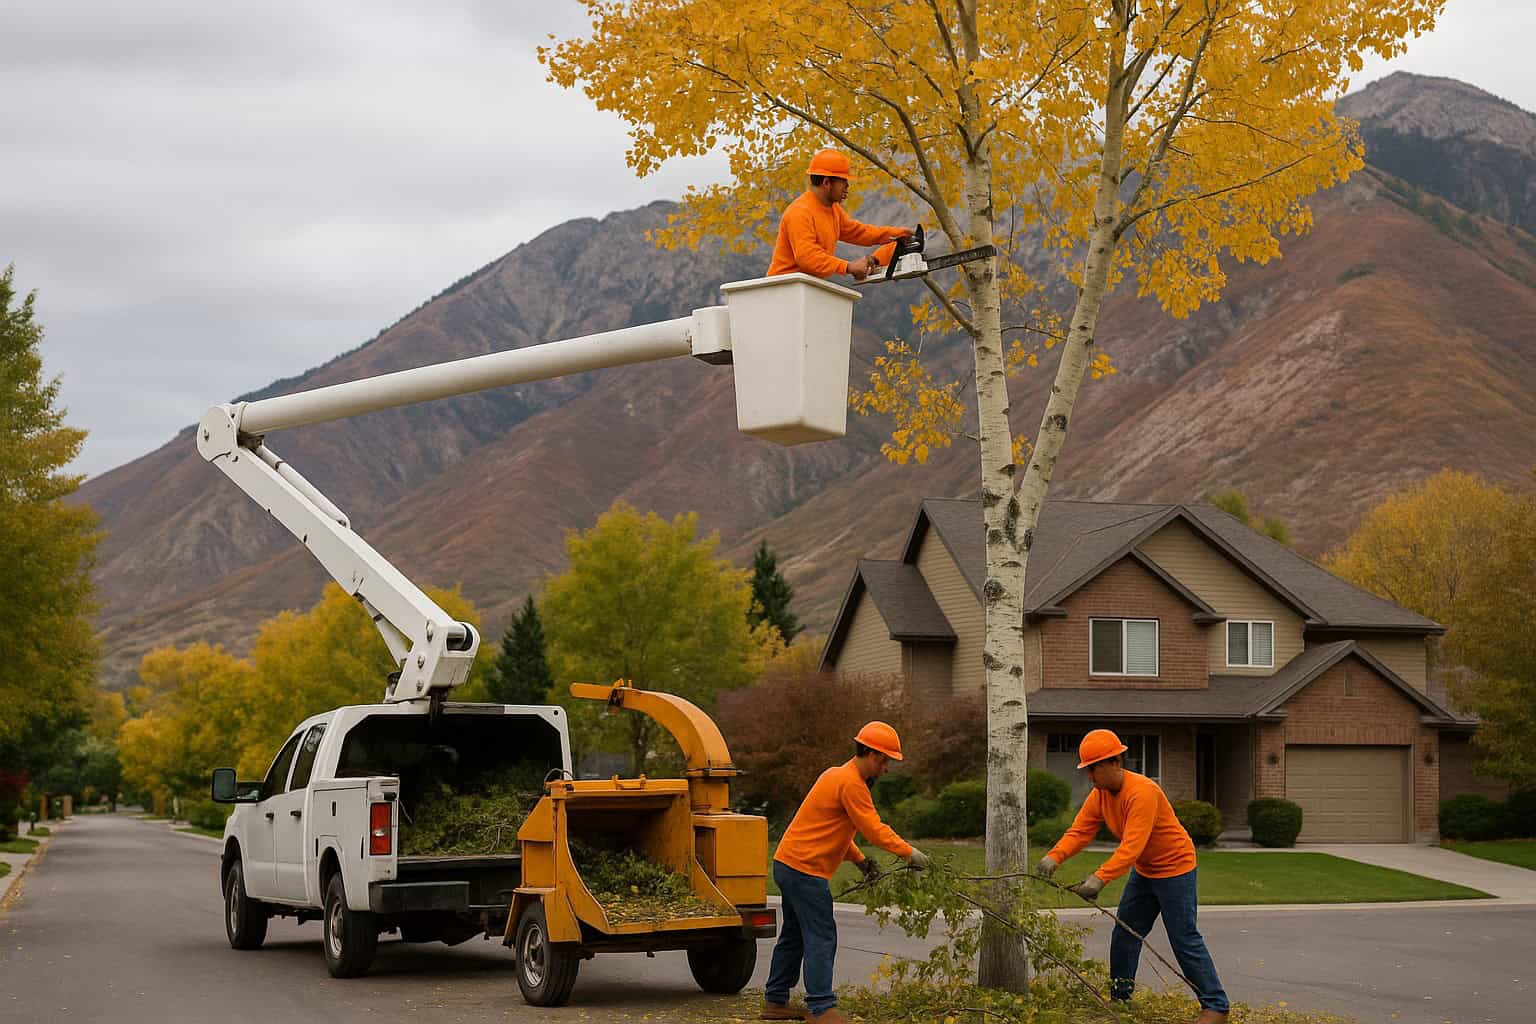
Commercial auto covers the trucks and chipper trailers your crews rely on to move between job sites across Salt Lake City and the Wasatch Front.
Inland Marine (Tools and Equipment)
Chainsaws, stump grinders, and crane attachments are covered wherever they travel across the state, whether stolen from a truck overnight or damaged on a job site.
Professional Liability (E&O)
Utah arborists who perform paid tree health assessments or wildfire-risk consulting should carry professional liability alongside general liability.
How Much Does Tree Service Insurance Cost in Utah?
General liability pricing in Utah falls in the same national range described on our tree service insurance page, roughly $750 to $2,300 per year for a small operation, driven by crew size, equipment, and whether wildland-urban interface wildfire mitigation work along the Wasatch Front is part of the regular business. Because Utah has no licensing requirement to screen out unprepared operators in this trade specifically, carriers underwriting a Utah tree service tend to weigh documented safety practices and claims history more heavily than they would for a licensed trade.
Key factors that drive Utah tree service premiums:
- Documented safety training and equipment maintenance practices
- Proximity of regular work to wildland-urban interface zones
- Payroll and crew size
- Prior claims history
- Municipal or utility contract requirements for higher limits
How The Allen Thomas Group Can Help You
We shop your general liability, workers compensation, commercial auto, inland marine, and professional liability across 15+ A-rated carriers, and in a state with no licensing requirement for this trade, a properly structured insurance program is one of the clearest ways a Utah tree company can demonstrate it runs a professional operation.
Licensing and Regulatory Notes for Utah Tree Care Businesses
Utah Administrative Code R156-55a-301(4)(c) specifically exempts tree stump and tree removal from the state's otherwise mandatory contractor licensing law, enforced by the Division of Professional Licensing. No arborist credential is required by the state; ISA Certified Arborist status remains voluntary. Utah's Workers Compensation Fund, founded in 1917, has since converted into fully private, Utah-domiciled stock insurance companies operating alongside other private carriers.
Because tree removal sits outside Utah's licensing system entirely, companies should lean on documented insurance coverage, safety training records, and ISA certification where held to demonstrate professionalism to customers who may not realize the trade is unlicensed. Companies working near the Wasatch Front's wildland-urban interface should also confirm any local wildfire-mitigation program requirements before quoting a job.
Common Utah Tree Service Claims and How Coverage Responds
Scenario 1: A Fence Is Damaged During a Salt Lake City Removal
A crew removing a large tree in a Salt Lake City neighborhood misjudges the drop zone and damages a neighbor's fence. This falls under the general liability policy's property damage coverage.
Scenario 2: A Climber Is Injured During a Large Removal
A climber falls and is injured while removing a large tree along the Wasatch Front. Workers compensation covers medical bills and a portion of lost wages.
Scenario 3: A Wildfire-Mitigation Assessment Is Later Disputed
A paid wildland-urban interface wildfire-risk assessment concludes a property's vegetation clearance is adequate, and it's later disputed after a fire. Because this is a professional-judgment claim, it falls to professional liability, not general liability.
Scenario 4: Equipment Is Stolen from a Job Site
A stump grinder is stolen overnight from a job site trailer near Salt Lake City. This falls under inland marine (tools and equipment) coverage.
Frequently Asked Questions
Does Utah require a contractor license for tree removal?
No. Utah Administrative Code R156-55a-301(4)(c), enforced by the Division of Professional Licensing, specifically lists tree stump and tree removal among the activities exempt from Utah's otherwise broad, mandatory contractor licensing law. This is a genuine carve-out: Utah runs one of the more comprehensive state contractor licensing systems in the country, and the legislature specifically excluded tree work from it by name.
Does Utah have its own workers compensation fund history?
Yes. Utah's Workers Compensation Fund began in 1917 when the state legislature passed an act mandating coverage and created the State Insurance Fund, later renamed the Workers Compensation Fund. Unlike Montana's or Colorado's funds, which remain state-affiliated, Utah's fund has since converted into fully private stock insurance companies, WCF Insurance Company among them, domiciled in Utah and A-rated by AM Best.
Does Utah require workers compensation for tree service companies?
Yes, standard private-carrier workers compensation applies to Utah tree service businesses, not one of the four monopolistic-fund states, with tree pruning and removal typically filed under NCCI classification 0106.
What insurance does a tree service business need in Utah?
Most Utah tree service businesses need general liability as the foundation, workers compensation, inland marine for chainsaws and stump grinders, commercial auto for trucks and chipper trailers, and professional liability if they perform paid tree health assessments or consulting work.
How much does tree service insurance cost in Utah?
General liability for a small Utah tree service operation typically falls in the same $750 to $2,300 per year range seen nationally, driven by crew size, equipment, and whether wildland-urban interface wildfire mitigation work is part of the regular business.
Does ATG write tree service insurance throughout Utah?
Yes. The Allen Thomas Group writes tree service insurance programs for companies across Utah, including Salt Lake City and the Wasatch Front. Call or request a quote to get started.
Get Your Utah Tree Service Insurance Program
The Allen Thomas Group is an independent, family-owned agency with access to 15+ A-rated carriers. One call gets you competitive rates from across the market, not a single carrier's take-it-or-leave-it quote. Certificates of insurance issued same day for active policies.