
Arizona Commercial Cleaning and Janitorial Business Insurance
The Allen Thomas Group is an independent, family-owned insurance agency that shops 15+ A-rated carriers to build coverage for commercial cleaning and janitorial companies across Arizona, not a single-carrier captive agent locked into one company’s rates and terms. We work with Arizona cleaning businesses of every size, from a single owner-operator to established janitorial companies running multiple crews across Phoenix, Scottsdale, and Tucson. Most quotes are ready within 1-3 business days. Click the button below to start your free quote, or call (440) 826-3676 to speak with a licensed agent directly.
Carriers We Represent


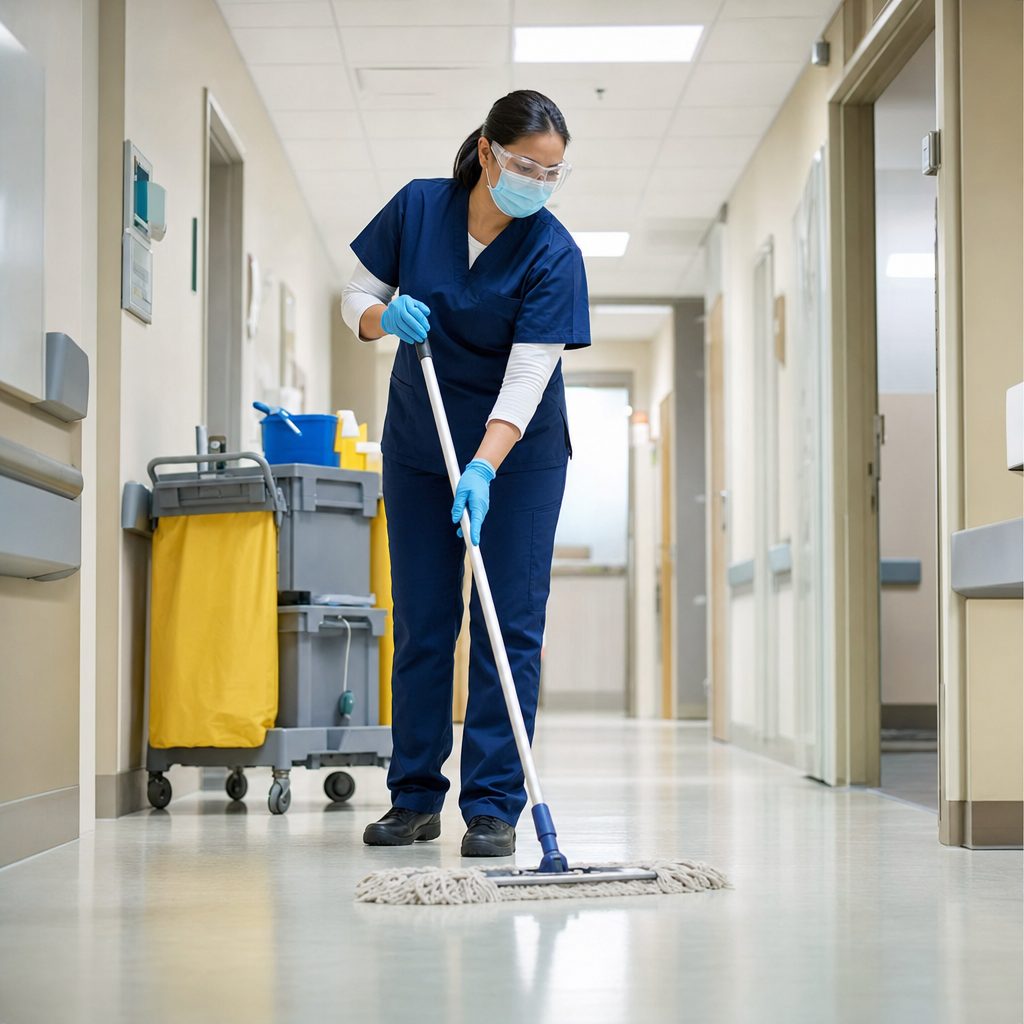
Commercial cleaning insurance in Arizona is a specialized bundle of coverage, typically general liability, a janitorial bond, and workers’ compensation, built around the specific risk of sending employees into other people’s offices and businesses across Phoenix, Scottsdale, and Tucson.
Why Commercial Cleaning Companies in Arizona Need Specialized Coverage
Arizona’s commercial cleaning industry is concentrated around its largest metro markets: Maricopa County (Phoenix, Scottsdale, Mesa, and Tempe) and Pima County (Tucson). Cleaning crews in these areas service everything from downtown Phoenix office towers to suburban medical buildings, retail centers, and corporate campuses, often working overnight or early-morning shifts across widely spread job sites. That range of building types and constant travel between locations creates exposures a standard business policy is not built to address.
A spilled degreaser or floor-stripping chemical can permanently damage marble or terrazzo flooring in a Scottsdale office lobby, leaving the cleaning company on the hook for replacement. A technician operating a floor buffer or carpet extractor in a Tucson medical building can suffer a strain or laceration serious enough to trigger a workers’ compensation claim. A lost master key or access fob at a downtown Phoenix high-rise can force a client into a full rekeying or access-control replacement, a bill the cleaning contractor is typically expected to cover.
Arizona-Specific Coverage Considerations for Commercial Cleaning Companies
Arizona does not issue or require a general state-level business license, and there is no license specific to commercial cleaning or janitorial services. A cleaning company registers its entity with the Arizona Secretary of State and, if it sells cleaning supplies or taxable goods directly, obtains a transaction privilege tax license through the Arizona Department of Revenue. Individual cities and counties may still require their own local business license, so companies operating across the Phoenix and Tucson metro areas should confirm requirements in each municipality where they hold contracts.
Arizona’s minimum wage rose to $15.15 an hour effective January 1, 2026, an increase of $0.45 that applies statewide under the Industrial Commission of Arizona‘s annual cost-of-living adjustment. Because workers’ compensation premiums for cleaning companies are calculated primarily on payroll within their classification code, a higher wage floor directly increases the payroll base the premium is built on, even before any change in claims experience. Cleaning companies budgeting for 2026 coverage should expect that payroll growth, not just rate changes, to push premium dollars higher.
- Arizona workers’ compensation runs through the private, competitive insurance market rather than a state fund, so cleaning companies shop coverage across competing carriers based on classification code, payroll, and experience modifier
- No dedicated state cleaning license exists; register the business with the Arizona Secretary of State and obtain a transaction privilege tax license from the Arizona Department of Revenue if selling supplies, then confirm any local city license requirement
- Mixed commercial and multi-tenant contracts across office, medical, and retail space often call for higher liability limits and additional insured endorsements to satisfy property manager contracts
- Extreme summer heat and monsoon dust storms common to the Phoenix and Tucson metro areas increase demand for exterior and window cleaning while raising heat-illness exposure for crews working outdoor or loading-dock areas
- Subcontractor requirements should verify that any subcontracted crew carries its own general liability and workers’ compensation coverage before being sent to a client site
- Equipment coverage protects buffers, extraction machines, and vacuums against theft or mechanical failure, a real risk given how far crews travel between job sites across the sprawling Phoenix metro
- Lost key and rekeying exposure is a recurring cost for crews servicing downtown Phoenix and Tucson high-rises, where a single missing master key or fob can trigger a full access-control replacement
Coverage Types for Commercial Cleaning & Janitorial Companies
Here’s what each policy actually covers, in plain terms, along with a link to the full coverage page where one exists:
General Liability Insurance
Covers third-party bodily injury and property damage your business causes while on a client’s premises.
Such as a client slipping on a wet floor after mopping, or a spilled chemical that damages a carpet. This is the coverage most commercial clients in Arizona require before signing a cleaning contract.
Janitorial Bond
A surety bond, not insurance, that reimburses a client if an employee steals money or property while cleaning their home or business.
It covers theft specifically, not accidental damage, and helps establish trust with Arizona clients who won’t hire an unbonded cleaning company.
Workers’ Compensation Insurance
Required in Arizona once a cleaning company has any employees, part-time or full-time.
Coverage is shopped across competing private carriers based on your classification code, payroll, and claims history.
Commercial Auto Insurance
Required for vehicles owned by the business, covering property damage and medical bills from an accident.
Used to transport crews, equipment, or industrial chemicals between job sites across Arizona.
Inland Marine (Tools & Equipment) Insurance
Covers cleaning equipment, such as floor buffers, carpet extraction machines, and ladders, while it’s in transit or on-site.
Commercial auto insurance covers the vehicle itself, not the equipment riding inside it, which is exactly the gap this coverage closes.
Business Owner’s Policy (BOP)
Bundles general liability with commercial property insurance into a single, typically lower-cost policy.
If you lease or own an office or storage space for your supplies, small, low-risk cleaning businesses are usually eligible.
Commercial Umbrella Insurance
Adds additional liability limits on top of general liability, commercial auto, and employer’s liability coverage.
Cleaning companies bidding on larger Arizona commercial contracts often need this to meet a client’s required liability limit.
Lost Key Coverage
Reimburses a commercial property for the cost of rekeying locks and reissuing keycard systems if your employee loses master keys.
Larger commercial and multi-tenant properties in Phoenix, Scottsdale, and Tucson increasingly ask about this coverage specifically before signing a contract.
Why Bonding and Insurance Matter for Arizona Cleaning Companies
Commercial cleaning crews are given access to offices, retail spaces, and sometimes homes across Arizona, often unsupervised and after hours. Property managers, business owners, and hosts of short-term rentals routinely require proof of both insurance and bonding before signing a contract or handing over keys and access codes. Being able to produce a certificate of insurance and proof of a janitorial bond on request is now a standard part of winning and keeping commercial cleaning contracts in Arizona, not an optional extra.
Related Coverage
Arizona Commercial Cleaning and Janitorial Business Insurance FAQs
Does Arizona require a special license for commercial cleaning businesses?
No. Arizona does not issue a general state business license for any industry, including cleaning. Companies register their entity with the Arizona Secretary of State and obtain a transaction privilege tax license from the Arizona Department of Revenue only if they sell supplies directly, plus any local license their city requires.
How much does workers’ compensation cost for a cleaning company in Arizona?
Arizona workers’ compensation runs through the private, competitive insurance market rather than a monopolistic state fund, so cleaning companies can shop coverage among competing carriers based on classification code, payroll, and experience modifier. Because Arizona’s minimum wage rose to $15.15 an hour on January 1, 2026, per the Industrial Commission of Arizona, overall payroll, and the premium calculated from it, has increased along with it.
Which Arizona cities have the most demand for commercial cleaning contracts?
Demand concentrates in the Phoenix metro, including Maricopa County cities such as Scottsdale, Mesa, and Tempe, and in Tucson in Pima County, where most of the state’s office towers, medical facilities, and retail centers are located.
What insurance does a commercial janitorial or cleaning company actually need?
Most commercial cleaning companies need four core policies: general liability insurance, workers’ compensation if you have employees, commercial auto insurance if crews drive between job sites, and a janitorial bond to reimburse clients for employee theft. Companies that lease office or storage space, carry expensive equipment, or bid on larger commercial contracts often add a business owner’s policy, inland marine coverage, and commercial umbrella insurance on top of those four.
What is a janitorial bond, and is it the same thing as insurance?
A janitorial bond, also called a fidelity bond or business service bond, is a type of surety bond, not insurance. It reimburses a client if one of your employees steals money or property while cleaning their home or business. Unlike an insurance claim, a surety company that pays out on a bond claim expects your business to reimburse it afterward, so it protects your client’s trust in you more than it protects your own bottom line.
Does my cleaning company’s insurance cover damage to a client’s property, or only theft?
General liability insurance covers accidental property damage, like a spilled cleaning chemical that ruins a client’s carpet. A janitorial bond covers something different: theft or dishonest acts by an employee. Most commercial cleaning companies need both, since they protect against two different kinds of loss.
Will my commercial auto insurance cover cleaning equipment I carry between job sites?
Not automatically. A standard commercial auto policy covers the vehicle itself and injuries or damage from an accident, not the buffers, vacuums, or extraction machines you’re transporting. Inland marine insurance is the coverage built specifically to protect cleaning equipment while it’s in transit or on a job site away from your main location.
How do I get in touch with a licensed agent about coverage for my cleaning company?
Call (440) 826-3676 to speak directly with a licensed agent, or request a free quote online and a licensed agent will follow up to go over the specific coverage your Arizona cleaning business needs.
Get Coverage Built for Your Arizona Cleaning Business
Talk to a licensed agent who will shop 15+ A-rated carriers to find coverage that actually fits your crews, equipment, and contracts.